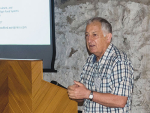
Agribusiness Expert Keith Woodford Receives ONZM
Retired agribusiness professor and commentator Keith Woodford says it's a great honour to receive the Officer of the New Zealand Order of Merit title in the King's Birthday Honours List.


 increase font size
 Keith Woodford
AN AGRIBUSINESS academic says Fonterra’s 2013-14 payout was unfair to sharemilkers and unshared suppliers as it ‘dipped’ the milk price to fund dividend-driving assets such Waitoa’s UHT plant and more milk hubs in China.
“The problem was they had to reduce the milk price to farmers to help fund these investments,” Lincoln University professor of farm management and agribusiness Keith Woodford told Dairy News.
“For most, that was simply a retention which became an asset, but for sharemilkers and those farmers who are not shared up it was non-compensated and hence an unfair transfer from them to those who do hold shares, including outside investors.”
Woodford says that with assets of $15.5 billion and liabilities of $9 billion, there are limits to how much Fonterra can prudently spend but if the cooperative wants to “stay up with the game” in international dairy or other FMCG markets it has to keep spending and its current and proposed investments are logical.
“Fonterra has good reason to believe whole milk powder will be the most profitable commodity product in the next few years, hence the focus on increasing capacity of whole milk processing. In this last year it was the limits on WMP processing that stopped the payout from being even higher,” he points out.
Powder investments such as Lichfield (circa $300m) should benefit milk price more than dividend but value-add investments such as Waitoa ($120m), a third Chinese milk hub ($340m split with Abbot) and the Beingmate partnership ($615m for a 20% stake), are for profit and dividend.
“The Waitoa UHT investment is important for Fonterra’s value adding strategies, particularly as they relate to China,” Woodford notes.
Similarly, more milk hubs in China will drive profit because good quality local milk there sells for exceptionally high prices, even at the farm gate.
“The co-investment with Beingmate also has a sound logic. It is far from risk free, but if Fonterra wants to move into value added activities it had to find a local Chinese partner and Beingmate is the obvious one.”
Woodford says Fonterra still suffers from having not retained earnings in its first few years and even now lacks mechanisms to acquire enough capital to put most of its milk into value-added consumer products. Consequently, it “has little option” but to persist as a commodity seller for the most part.
“But being a producer of dairy commodities is not necessarily bad. This is particularly the case for Fonterra, given that Fonterra remains the world’s most efficient processor and marketer of dairy commodities. It is also lower risk than investing in consumer products for overseas markets.”
If Fonterra again raids the milk price to fund value-add investments it seems it will be doing little to endear itself to sharemilkers who, traditionally, would be the shareholders of the future. “It will be grossly unfair to sharemilkers,” Woodford says.
Retired agribusiness professor and commentator Keith Woodford says it's a great honour to receive the Officer of the New Zealand Order of Merit title in the King's Birthday Honours List.
Fonterra has reduced its 2020-21 forecast farmgate milk price range midpoint by 5c.
Agribusiness expert Keith Woodford is warning that the chances of eradicating Mycoplasma bovis are not high.
The A1 versus A2 debate has the potential to tear the industry apart.
Agribusiness consultant Keith Woodford is a big fan of composting dairy barns.
Farmers have until the end of this week to help shape DairyNZ’s future focus.
Wayne McNee, chief executive of AgriZeroNZ, has resigned and will leave the organisation on 15 January 2027.
The New Zealand dairy sector set a record in the 2025/26 season, producing more than two billion kilograms of milksolids for the first time.
Milk powder prices are continuing their merry run, firming up a potential $10/kgMS farmgate price this season.
Teachers are welcoming the outgoing Government’s U-turn allowing agriculture and horticultural science to remain a standalone Year 11 subject.
Outgoing ACT MP and dairy farmer Mark Cameron says Saturday’s election result reflects voters deeply impacted by the cost of living.
OPINION: It seems Canterbury processor Synlait is still in the doldrums.
OPINION: Get offside with New Zealand First leader Winston Peters at your own peril.