Fonterra FY26 Results: $9.69 Milk Price, $3.4bn Profit
Fonterra has unveiled its annual results for the 2026 financial year, posting $27 billion in revenue and close to $20 billion returned to New Zealand farmer owners and unit holders.


 increase font size
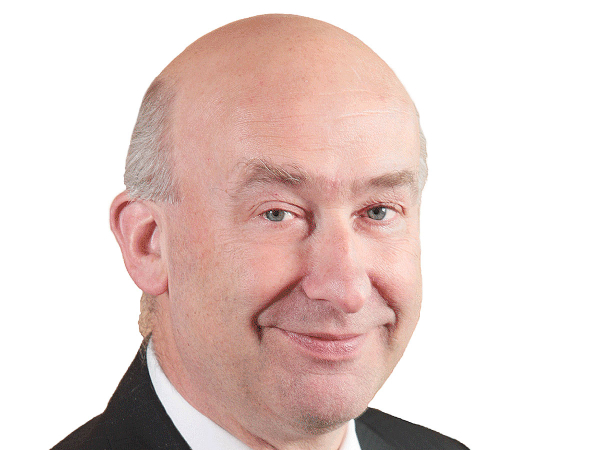 Craig Macalister, Findex.
Fonterra farmers are set for a multi-billion-dollar payout this week.
Fonterra is returning $2/share to shareholders and unit holders, after the divestment of Mainland Group to Lactalis, which was completed two weeks ago.
The capital return has been achieved by way of a pro rata share buyback from shareholders.
The co-operative is believed to have obtained a binding ruling from Inland Revenue that the amount paid to shareholders under a share buyback arrangement will be treated as a return of capital and not as a dividend for income tax purposes. This means the proceeds will not be taxable in shareholder's hands.
Since the announcement of the sale of the consumer brands businesses, there has been speculation about how the return to shareholders might be used. Suggestions have included retiring debt, addressing deferred farm maintenanced, upgrading farm plant and equipment, expanding the farm or herd size, putting funds into investment products, or even enjoying a good old "knees up" at the local bar and grill - or all of the above.
However, Craig Macalister, a partner with Findex, has raised concerns that no discussion on this, that he is aware of, references the structure of the shareholder ownership and the implications using the funds for things other than reinvesting into the farm business. In this regard, Macalister notes that if the Fonterra shareholding is held by a company, taking the funds out of the company without tax implications is not likely to be possible.
Macalister explains: "With a company structure, if shareholders want to take any capital gain amounts out tax-free, the company has to be wound up." While New Zealand does not have a capital gains tax, as a general rule, capital gain amounts cannot flow through a company tax-free.
Instead, any distribution from the company, unless it is wound up, will be treated as a taxable dividend. Shareholders can take drawings out of a company, but if this overdraws the current amount, interest at FBT rates must be paid to avoid a deemed dividend. While this may be manageable short term, it essentially amounts to paying taxable interest to oneself and is not a sustainable position over the long term.
Thus, if the shareholding is held by a company, spending funds on things that are not assets of the company, such as holidays or a new car, cannot be done without triggering tax consequences.
Macalister urges shareholders to consult with their accountant before finalising decisions on how the capital return is to be spent.
Fonterra has unveiled its annual results for the 2026 financial year, posting $27 billion in revenue and close to $20 billion returned to New Zealand farmer owners and unit holders.
Fonterra Co-operative Group has confirmed the independently assessed candidates standing for election to its board in 2026.
Fonterra has revised its Farmgate Milk Price forecast for the 2026/27 season, lifting the midpoint and narrowing the range on the back of improving global dairy commodity prices.
Outgoing Fonterra Co-operative Council chair John Stevenson says that it has been a privilege to represent the co-op's farmer shareholders.
OPINION: Succession and long-term planning are perennial topics because it is perpetually sidelined on busy farms.
LIC shareholders have elected a new North Island representative to the co-operative's Board, along with five representatives to its Shareholder Reference Group (SRG), following the company's Annual Meeting held in Invercargill.
Farmers across parts of Southland and South Otago are continuing to deal with difficult conditions after a prolonged run of wet weather, with pressure building around feed supply, stock management, pasture damage, farm infrastructure and everyday workloads.
Federated Farmers says it welcomes Labour's commitment to reviewing the Sharemilking Agreements Act, calling on other major parties to do the same.
For Canterbury dairy farmers Sian Meijer and Rick Wobben, wearable technology has become one of their most valuable on-farm tools - helping manage 1850 cows across an expansive, high-performing dairy operation while improving efficiency, mating outcomes and day-to-day decision making.
Fonterra has unveiled its annual results for the 2026 financial year, posting $27 billion in revenue and close to $20 billion returned to New Zealand farmer owners and unit holders.
The first major update to the Dairy Cattle Code of Welfare in more than a decade has been released, marking what DairyNZ describes as an important step in ensuring animal welfare standards continue to evolve alongside scientific evidence and on-farm realities.
OPINION: It seems Canterbury processor Synlait is still in the doldrums.
OPINION: Get offside with New Zealand First leader Winston Peters at your own peril.