Regulation strangling agribusiness
OPINION: It's not regulation that's the major issue for New Zealand's farmers.


 increase font size
 Crowe Horwath spokesman Hayden Dillon.
With an 80% likelihood the Reserve Bank will lower the official cash rate by 25 basis points next month, many rural borrowers are wondering if now is the time to look at fixing rates.
Crowe Horwath spokesman Hayden Dillon cautions that with markets still volatile, it is risky to make hedging decisions based on economists’ advice.
“Even with another cut appearing imminent, the market appears to have little appetite for more,” he says. “Inevitably talk will begin about when rates may start to go up.
“Many rural borrowers are now looking at an interest rate curve that is still relatively flat, and are thinking now could be the time to take some cover. But there are variables you need to be aware of.”
In this new era of banking, banks are being set higher hurdles by regulators to maintain their stability. Some banks have added extra clauses to lending agreements. Dillon advises rural borrowers to ask the right questions and fully understand all the relevant clauses before accepting bankers’ fixed rate offers.
“Understand exactly what you are agreeing to before signing for any fixed rate deal. Since the global financial crisis lenders have adjusted clauses in fixed term rates to provide themselves with more flexibility to exit the loan if they are not comfortable with the credit conditions.
“In the event your credit position deteriorates, some contracts will allow the bank to exit the fixed loan, and any costs are borne by the client. So you must fully understand exactly what your agreement with your lender means.”
The global financial crisis also brought in new central bank regulations from the government for banks to comply with.
While these changes have created legitimate additional costs, they should not be used as an opportunity for banks to obtain a few extra points at the borrower’s expense.
“You need to ensure there is transparency in your pricing. Whatever your credit position, you want to ensure you are getting the best possible outcome for your business.”
There are various ways to do this and Dillon says the best way will depend on the business’ credit position and the type of lending facilities being used.
“Each bank has its own yield curve; this means that even though you may have the same credit margin as your neighbour, each bank has a different cost of funds for the lending so your ‘all up rate’ will be different.”
Given risks such as Brexit, farmers should work on their own hedging strategy, taking into account those risks and their ability to manage them.
“Once you ask yourself ‘what if’ questions to assist in establishing a hedging framework, you will find it easier to act proactively, rather than being reactive to market commentary,” says Dillon.
OPINION: It's not regulation that's the major issue for New Zealand's farmers.
OPINION: Perhaps Captain Bligh’s infamous line, “the beatings will continue until morale improves”, best summed up the mood of New Zealand’s weary agribusiness sector at Fieldays last year.
The farming community needs to step up to help lessen the rift between city and country.
Market commentators are indicating with 80% certainty the Reserve Bank of New Zealand will lower the official cash rate by 25 basis points next month and then it will begin to stabilise.
With volatility in the dairy payout, there has never been a more important time to have a clear picture of your farming business’ performance, says Dairy Women’s Network.
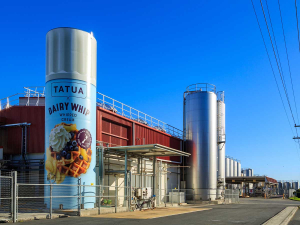
Waikato milk processor Tatua has again declared a record milk payout to farmer shareholders, leaving other processors in the dust.
A Labour-led Government won’t be bringing back the controversial freshwater rules of 2020.
National’s much-touted free trade deal with India featured in the Rural Issues Debate at Mystery Creek, Hamilton on Wednesday night.
New Zealand's 2026-27 freshwater fishing season has opened, with anglers encouraged to head to rivers and lakes over the coming days as conditions look favourable across much of the country.
Central Otago District Council (CODC) has voted against a plan to spread treated sewage sludge from Cromwell and Alexandra on farmland near Lauder, a decision Federated Farmers says reflects strong opposition from rural residents.
Pāmu has released its FY26 Integrated Annual Report, reporting a Net Operating Profit of $113 million, more than double the $49 million recorded in FY25.
OPINION: The same mainstream media muppets that brought you Jacindamania in 2017 have been flat out pimping for the Opportunities…
OPINION: Your old mate reckons the atrocious way farmers in the UK are treated by their lords and masters in…