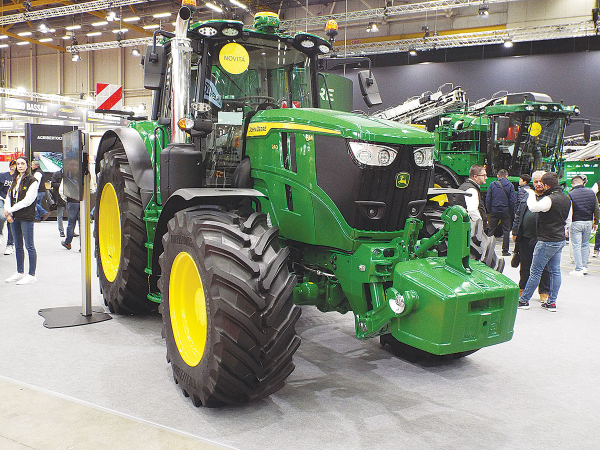
With the last couple of months having seen some potential tractor purchases put on hold with the impending election and continued input cost rises, year-to-date figures, ending September, has seen deliveries up around 5% over the same period in 2025, with a total of 2026 units.
September saw 344 tractors delivered – down about 6.3% over last year’s 367 units – with the overall result a tale of two islands: the North Island down 25% (164 v 218), and the mainland up by 21% (180 v 149).
Looking at the makeup of the tractors being sold, year-to-date, 535 units (24%) were tractors of 60hp or less, generally described by the industry as ‘lifestyle machines’. This was followed by 269 units (12%) models from 60 - 100hp, typically finding homes as secondary units on dairy farms, alongside beef, dairy, orchard and vineyard operations.
At the heart of the market, 1155 tractors (51.1%) were in the key 100 - 180hp sector, finding a wide range of uses for farmers and contractors, while 295 units (13.05%) were in
the 180 - 375hp sector, followed by only five machines (0.6%) of more than 375hp.
The segmentation confirms the thoughts of one industry stalwart who always said, “There’s far more snapper waiting to be caught than marlin”.
Indeed, the South Island looks to be driving overall results, with year-to-date numbers of 920 units, up around 20% over 2025. That number is dominated by the 100-150hp and 150-200hp sectors, up 23.3% and 39.4% respectively ahead of last year, whilst in the North Island, deliveries were behind in all horsepower categories.
From a rolling 12-month perspective, total deliveries of 3195 units, compared to 3061 for the same period last year, might suggest that once the election and input costs stabilise, the market will continue to improve.